

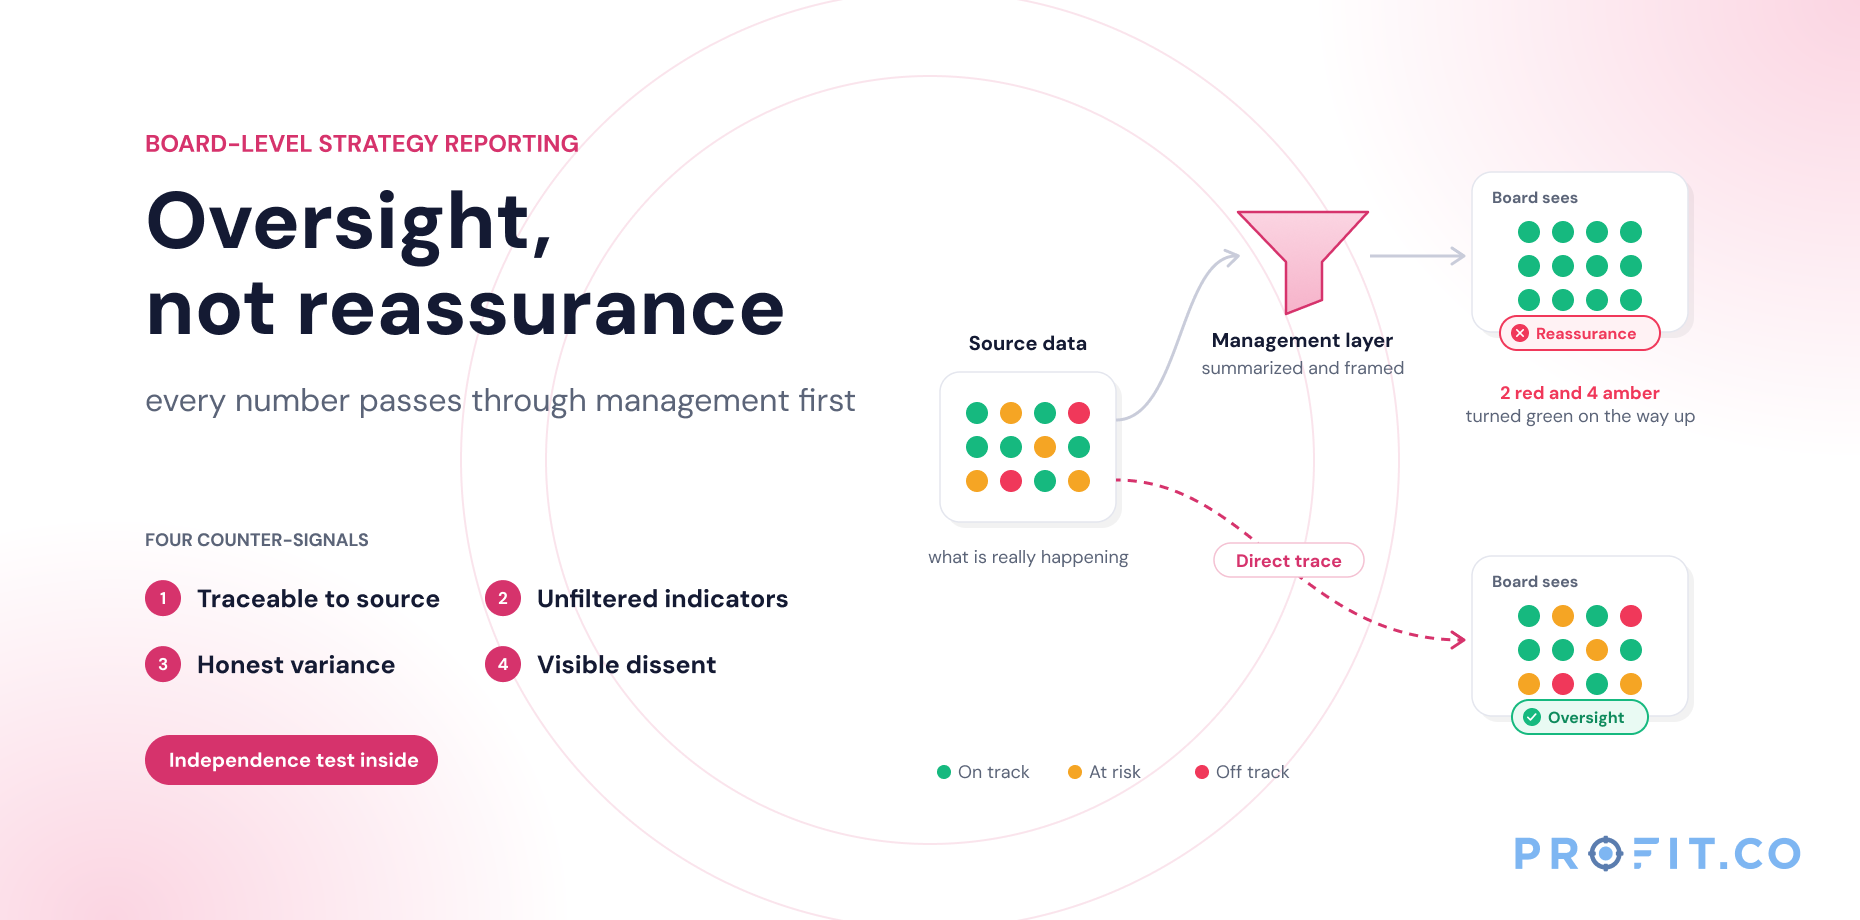
A board is asked to oversee a strategy using information prepared entirely by the people being overseen. No format fixes that. Design has to.
Board-level strategy reporting exists to enable oversight, which is a different job from keeping the board informed. Its central design problem is filtration: every figure reaching a board has passed through the management layer the board is assessing, and boards meet too infrequently to detect distortion from the reports alone. Four signals counteract this, traceability from any claim back to its source record, unfiltered leading indicators that management has not curated, variance honesty visible across periods rather than within one, and pending decisions and dissent surfaced rather than resolved before the pack is written. A board report that produces confidence without supporting challenge has failed, however well it is constructed.
Table of Contents
In this article
- What Board-Level Strategy Reporting Is Actually For
- The Filtration Problem
- Oversight Versus Management: The Line That Defines Content
- Signal 1, Traceability From Claim to Source
- Signal 2, Unfiltered Leading Indicators
- Signal 3, Variance Honesty Across Periods
- The Four Oversight Signals
- Signal 4, Pending Decisions and Visible Dissent
- The Annual Rhythm: What the Board Should See When
- What Boards Ask That Reports Fail to Anticipate
- Three Board Packs, Read Against the Independence Test
- Five Failure Modes of Board Strategy Reporting
- The Independence Test
- Building the Board Reporting Standard
- Frequently Asked Questions
Key Takeaways
- Oversight is not the same as being informed: a board that understands the strategy but cannot challenge the account it was given has been briefed, not equipped. Reporting design has to serve the second.
- Filtration is the structural problem: every number reaching the board passed through the layer being assessed, and boards meeting four to six times a year cannot detect distortion from the pack alone.
- Traceability is the strongest single counterweight: when a board can follow any claim back to the owner, the check-in, and the timestamp that produced it, the incentive to smooth numbers largely disappears.
- Some indicators must reach the board uncurated: check-in discipline and confidence distributions are system-generated and lose their value the moment they are summarized into a narrative.
- Report variance across periods, not within one: a single quarter’s variance is explainable. Four quarters of variance in the same direction is a pattern, and only the board is positioned to name it.
- A pack with no open questions is a warning sign: if every issue has been resolved before the board sees it, the board is reviewing decisions rather than participating in them.
1. What Board-Level Strategy Reporting Is Actually For
Board reporting is routinely designed as though its purpose were to keep the board informed. That is part of it, and the smaller part. The board’s function is oversight, monitoring the strategy, questioning the account of it, and holding management accountable for execution on behalf of shareholders or members. Reporting exists to make that function possible.
The distinction has practical consequences for content. A report designed to inform answers the questions management expects. A report designed for oversight answers the questions a sceptical director would ask, including the uncomfortable ones, before they are asked. The first produces a smooth meeting. The second produces a useful one.
Why this gets designed wrong
Board packs are prepared by management, and management has a reasonable instinct to present its work well. Nobody sets out to obscure. But the accumulated effect of many small, defensible presentation choices, leading with the strongest priority, summarizing a difficult area, omitting a metric that would need explaining, is a document that supports confidence more readily than challenge.
Profit.co names a related pattern in its analysis of balanced scorecard failures: without top-level ownership, the scorecard becomes a reporting tool rather than a strategic driver. The same degradation happens to board reporting. Once its purpose becomes producing the pack rather than enabling oversight, the pack gets longer and the oversight gets thinner. The full list is in ten balanced scorecard mistakes that kill strategy execution.
2. The Filtration Problem
Here is the structural condition every board operates under. The board is accountable for overseeing the strategy. All the information it uses to do so is selected, aggregated, and narrated by the management team whose execution it is assessing. The board meets four to six times a year and has no independent operational visibility between meetings.
This is not an accusation. It is a description of the arrangement, and it holds even where management is entirely straight. Filtration is mostly unconscious:
- Selection. Which metrics appear at all. A metric that would require a difficult explanation is often simply not included, and its absence is invisible to the board.
- Aggregation. Rolling up to a level where variation disappears. Three departments at 95%, 70%, and 45% average to a reassuring 70%.
- Narration. Attaching an explanation to a number before the board sees it. The explanation may be correct, but it arrives having pre-empted the board’s own interpretation.
- Timing. Reporting a figure as of a date that flatters it, without stating the as-of date prominently enough for anyone to notice.
Why format improvements do not fix it
Most board reporting advice addresses clarity, shorter packs, better visuals, executive summaries. All worthwhile, none responsive to filtration. A beautifully clear report built on selected data is more persuasive than a cluttered one, which arguably makes the problem worse. The counterweights are structural, and the rest of this article works through four of them.
3. Oversight Versus Management: The Line That Defines Content
Before deciding what a board report contains, it is worth being precise about what boards do and do not do, because most bloated board packs are the result of an unclear line.
What sits with the board
- Strategic direction and its continued validity. Whether the strategy remains the right one given what has changed.
- Resource allocation at portfolio level. Whether major investments serve the strategy, not whether individual projects are well run.
- Risk appetite and material risk exposure. Which risks the organization accepts, and whether any have moved beyond tolerance.
- Executive accountability. Whether management is executing competently against the direction set.
What sits with management
- Everything about how. Delivery approach, sequencing, team structure, tooling, individual project recovery.
- In-cycle reallocation. Moving resources between initiatives inside an agreed envelope.
- Operational risk resolution. Working risks to closure, escalating only those that cross into material.
Content that supports no board decision should not be in the pack. This sounds obvious and is violated constantly, usually because a director once asked about something and it became a permanent section. The discipline required is the same one that keeps a strategy office from drifting into delivery: reporting on execution is oversight, and reporting on how execution is being performed is management. The boundary is explored from the strategy-function side in Profit.co’s material for strategy and transformation leaders.
4. Signal 1, Traceability From Claim to Source
Counteracts: selection and narration.
Traceability means a director can take any claim in the pack and follow it back to the record that produced it, the objective, its owner, the check-ins behind its progress, and the date each was entered. Most boards cannot do this, which is why most board discussions about numbers end in an assurance rather than a resolution.
What changes when traceability exists
The obvious benefit is verification. The more important one is behavioural. When any figure can be traced to an owner and a timestamp, the incentive to smooth it largely disappears, because smoothing becomes detectable rather than merely unlikely to be questioned. Traceability does most of its work before the pack is written.
What makes it possible
- A single source of truth beneath the pack. Where OKRs, projects, and performance data share one system, a board figure has a lineage. Where the pack is assembled from four systems by hand, it has a provenance nobody can reconstruct under questioning.
- Fund-to-goal linkage. Profit.co connects every project to the OKR it supports, giving traceability from business case approval through benefits realization, which is what allows a board to ask which funded work serves a given strategic priority and get an answer rather than an undertaking to follow up.
- Immutable activity logs. Profit.co’s Governance module records every change to a governance item automatically with the acting user and timestamp, across eight independently configurable categories, Actions, Assumptions, Decisions, Issues, Risks, Strategic Alignment, Project Changes, and Tollgates. For a board, the Decisions category is the one that matters most: it records what was chosen, what alternatives were considered, and the rationale.
A practical test for your own pack: pick one number at random and ask how long it would take to produce the underlying record with its owner and date. If the answer is more than a few minutes, the board does not have traceability, whatever the pack claims.
5. Signal 2, Unfiltered Leading Indicators
Counteracts: narration and aggregation.
Some indicators should reach the board exactly as the system computed them, with no summarizing layer. These are the ones whose diagnostic value lives in their distribution, and summarizing destroys it.
The candidates
- Check-in discipline. Broken into Missed, Late, On time, and Pending, with the departmental breakdown intact rather than rolled to an organizational average. A single figure of 82% tells a board nothing; 82% composed of one department at 96% and another at 51% tells it a great deal.
- Confidence distribution. In Profit.co, confidence and progress are recorded independently, and each status maps to a configurable confidence percentage. A distribution with no spread, every owner reporting the same confidence week after week, indicates defaulting rather than forecasting, and it is only visible in the raw distribution.
- Status movement over time. The Cockpit displays how OKRs are distributed across On Track, At Risk, In Trouble, Completed, Not Started, and Archived and how those shift across periods. Churn between bands is invisible in any snapshot and highly informative about execution stability.
The rule
Present these as generated, alongside management’s commentary rather than replaced by it. The board should be able to read the system’s account and management’s account of the same period and notice where they differ, which is precisely the comparison filtration removes. The underlying instrumentation is documented across Profit.co’s insights, analytics, and reports.
6. Signal 3, Variance Honesty Across Periods
Counteracts: timing and narration.
Any single quarter’s variance has an explanation, and usually a legitimate one. Markets move, a hire slipped, a dependency failed. Management supplies the explanation, the board accepts it, and the matter closes. Repeat that four times and a pattern has gone unnamed, because no individual instance was unreasonable.
What the board needs to see
- Planned against actual across the full year, not the quarter. Profit.co’s project overview shows actual and planned progress together with a plain-language variance label and a marker for where planned progress sits today, so the comparison basis is explicit rather than assumed.
- The direction of successive variances. Four quarters of shortfall against plan is a forecasting problem regardless of how good each individual explanation was. This is a board-level finding by nature: nobody inside the management layer is positioned to name it.
- The progression model behind the plan line. Profit.co supports five models, Linear, Front-loaded, Back-loaded, S-curve, and Stepped. A board looking at apparent underperformance on back-loaded work is looking at an artefact, and a board that is never told which model applies cannot tell the difference.
The question this signal enables
“Is this quarter unusual, or is this what our forecasting looks like?” A board that can ask that with evidence is exercising oversight. A board that can only respond to one quarter at a time is being managed.
7. The Four Oversight Signals
The table below maps each signal to the filtration it counteracts, what it requires, and the question it lets a board ask with evidence behind it.
| Signal | Filtration It Counteracts | What It Requires | Question It Lets the Board Ask |
|---|---|---|---|
| 1. Traceability from claim to source | Selection and narration | Single source of truth; fund-to-goal linkage; immutable activity logs | “Show me the record behind this number, who owns it and when was it entered?” |
| 2. Unfiltered leading indicators | Narration and aggregation | System-generated distributions presented intact, not rolled to an average | “Which departments sit behind this figure, and how far apart are they?” |
| 3. Variance honesty across periods | Timing and narration | Planned-vs-actual across the year; stated progression models | “Is this quarter unusual, or is this what our forecasting looks like?” |
| 4. Pending decisions and visible dissent | Selection | Open items surfaced rather than resolved before the pack is written | “What did you disagree about, and who decided?” |
None of the four is a formatting change. Each requires either an architectural property of the underlying system or a deliberate choice by management to present something it would be more comfortable summarizing. That is the honest position: board reporting quality is largely determined before anyone opens a slide template, which is why it tends to improve only when the reporting standard is set by the board rather than proposed by management. Related discipline for the review layer beneath the board is covered in running strategy reviews that actually change execution.
Give your board traceability from any claim back to its source record
8. Signal 4, Pending Decisions and Visible Dissent
Counteracts: selection.
The most reliable indicator that a board pack has been over-filtered is that it contains no open questions. Every issue arrives resolved, every risk arrives mitigated, every decision arrives made. The board’s role has been reduced to noting.
This happens for understandable reasons. Bringing an unresolved disagreement to a board feels like admitting the executive team could not settle it. In practice, the opposite reading is correct: a management team confident enough to show the board a live question is a management team that is not managing the board.
What to surface
- Decisions genuinely pending. Named, with the options and the date by which a choice is needed. Profit.co’s Governance module carries a Decisions category recording the choice made, the options considered, and the rationale, which makes a pending decision a record rather than a conversation.
- Assumptions not yet validated. The Assumptions category covers factors believed true for planning that still require validation and carry risk if wrong. For a board assessing strategic direction, unvalidated assumptions are frequently more material than any current issue.
- Material risks with owners and current state. Not a count. The specific ones that could affect strategic objectives, each with an owner and where it stands, supported by the escalation path from Risk to Issue, which cross-links both records and preserves the history on each.
- Where the executive team did not agree. Rare in practice and disproportionately valuable. A board that only ever sees consensus has no way to calibrate how much consensus is worth.
A useful standard to set: every board pack carries at least one genuinely open item. If a quarter produces none, that is itself worth a question.
9. The Annual Rhythm: What the Board Should See When
Not every signal belongs in every meeting. A board seeing the same content four times a year stops reading it, and a board seeing everything at once cannot prioritize. The rhythm below assumes four scheduled meetings.
| Meeting | Primary Focus | What Is Heavy | What Compresses |
|---|---|---|---|
| Q1, Cycle open | Is the plan sound and owned? | Strategic priorities, coverage, assumptions not yet validated | Progress, which barely exists yet |
| Q2, Early execution | Is it moving as expected? | Unfiltered leading indicators; early variance; pending decisions | Financial detail, unless a threshold has been crossed |
| Q3, Mid-cycle correction | Does anything need to change? | Variance across periods; portfolio reallocation; material risks | Coverage, which was settled in Q1 |
| Q4, Close and refresh | What did we learn, and what next? | Full-year variance; benefits realized vs promised; assumption outcomes | In-period status, now superseded by outcomes |
Two design notes. First, traceability is not in the table because it is not a meeting-specific item, it is a standing property the pack either has or does not. Second, Q4 is the meeting most commonly wasted. Treated as a results summary it adds nothing the board could not infer; treated as a diagnosis of what the system learned, it is the meeting that shapes the next year. The same distinction separates programmes that compound from those that plateau, examined in why most enterprise OKR programs fail in year two.
10. What Boards Ask That Reports Fail to Anticipate
Six questions come up repeatedly across boards, and packs routinely fail to pre-empt them. Each one costs meeting time that could have gone to the decision.
“As of when?”
Asked because data currency is the first thing a sceptical director tests. Pre-empt it with a one-line evidence note stating the as-of date for each major figure. This single line saves more meeting time than any other change available.
“Compared to what?”
A percentage with no stated basis is three different claims, against plan, against prior period, or against target. Name the basis on the figure rather than in a footnote.
“What would change your mind?”
Directed at management’s confidence in the strategy. It is answerable only if the pack states which assumptions the strategy rests on, which is why the assumptions block matters more than its usual prominence suggests.
“Who owns this?”
Asked of any red item. A pack listing exceptions without named owners forces a live lookup, and the answer is often vaguer than it should be.
“What did we decide last time, and what happened?”
The question that exposes whether the board is running a loop or a series of disconnected meetings. Carry forward prior decisions with their current state, Profit.co’s Decisions category and immutable activity logs make this a lookup rather than a reconstruction.
“Is this the whole picture?”
Rarely asked directly, always present. The only durable answer is traceability: a board that can verify does not need to ask.
11. Three Board Packs, Read Against the Independence Test
Three composite scenarios, each drawn from patterns that recur across strategy functions. Read each against the test in Section 13: could a director, using only the pack, reach a conclusion that differs from management’s?
Pack A, The quarter that averaged well
A manufacturing group reports 74% progress against its four strategic priorities, with commentary describing steady execution and one priority flagged amber for supply-chain reasons. The pack runs eleven pages. Every figure is accurate.
What a director cannot do with it: form an independent view. The 74% is an organizational roll-up across four priorities and eleven departments, and the pack contains no distribution beneath it. The amber flag arrives with its explanation already attached, so the board’s options are to accept the supply-chain account or to ask for something the pack cannot supply.
What the four signals would have added: the departmental spread behind the 74% (Signal 2), which in this case ran from 96% to 41% and located the problem somewhere other than supply chain; and the same four priorities plotted across the prior three quarters (Signal 3), which showed the amber priority had been amber every quarter with a different explanation each time. Neither required new data, both existed in the system and were removed by aggregation.
Pack B, The pack with a question in it
A financial services firm brings its board a pack of six pages. Five cover the strategic priorities in a fixed structure unchanged for two years. The sixth is headed “Open: market-entry sequencing” and sets out two options the executive team did not agree on, with the case for each, the date a decision is needed, and which assumption each option depends on.
Why this passes: the board is participating in a decision rather than noting one. The disagreement is visible, so directors can weigh the reasoning rather than the conclusion. The dependent assumptions are named, which means the board can ask what would invalidate each option, the question Section 10 identifies as usually unanswerable.
The uncomfortable part: this pack is harder to write, and the executive team has to show the board that it did not reach consensus. That is precisely what makes it useful. A management team confident enough to bring a live question is not managing its board.
Pack C, The traceability failure
A technology company’s board asks a routine question about a figure in the portfolio section: which funded initiatives sit behind the reported spend against the growth priority? The CFO undertakes to follow up. The answer arrives eleven days later and does not reconcile with the pack, because the pack was assembled from a finance export and a separate delivery export taken on different dates.
What actually failed: not the pack and not the CFO. The organization had no single source of truth beneath the reporting layer, so no figure in it had a lineage anyone could reconstruct under questioning. Where projects link directly to the objectives they serve, this question is a lookup rather than a reconciliation project, which is what fund-to-goal traceability from business case through benefits realization is for.
The second-order cost: the board learned that verification is expensive, so it stopped asking. Six meetings later the pack had grown to twenty-two pages, because directors who cannot verify compensate by requesting more detail. This is the mechanism described in Section 13, independence is the cheaper equilibrium, and Pack C shows what the expensive one looks like.
The pattern across all three: in every case the information the board needed already existed inside the organization. It was lost to aggregation, pre-empted by narration, or made unreachable by assembly. None of the three was a failure of effort or intent, which is why board reporting quality does not improve through trying harder, it improves through changing what the pack is required to carry. The same distinction between producing a report and enabling a decision runs through running strategy reviews that actually change execution.
12. Five Failure Modes of Board Strategy Reporting
1. The reassurance pack
Every priority green, every risk mitigated, no open questions. Reads well and supports no oversight. The diagnostic is simple, count the items in the pack that could lead a director to challenge management. If it is zero, the pack is a briefing.
2. Aggregation to the point of meaninglessness
Everything rolled to organizational level. Variation is where the information lives, and averaging is the most common way it is lost, usually without anyone intending to lose it.
3. Delivery detail in a governance forum
Project status, sprint progress, task completion. This content belongs to management. Its presence in a board pack crowds out strategic content and, more subtly, invites directors into operational conversations they are not positioned to have well.
4. The append-only pack
Sections added whenever a director asks a question, none ever retired. After two years the pack is sixty pages and the strategic content is somewhere in the middle. The fix is a fixed page budget where additions require retirements.
5. Hand-assembled from exports
Numbers copied from several systems into slides. Accurate on the day built, stale within a week, and impossible to defend under questioning. Profit.co generates PDFs, PowerPoints, and email summaries directly from live goal data, removing the assembly stage between the record and the pack, and with it the reconciliation risk. Gerardo Haro at Intuitive Surgical reports an 84% reduction in time spent building PowerPoints for executives, among Profit.co’s customer stories.
13. The Independence Test
A single test covers most of what this article argues. Take the board pack and ask: could a director, using only this document, reach a conclusion that differs from management’s?
If the answer is no, the pack is a briefing. It may be accurate, well-constructed, and genuinely useful for understanding the business, and it still does not support oversight, because oversight requires the capacity to disagree on evidence.
What passing looks like
- Raw distributions are present, not only summaries. A director can look at the departmental spread and form their own view of where the problem sits.
- Comparison bases are stated. A director can check whether a figure is flattering because of the basis chosen.
- Multi-period variance is visible. A director can see a pattern management has explained away one quarter at a time.
- Open items exist. A director has something to form a view about rather than something to note.
Why management should want this
The instinct is to read independence as adversarial. It is the opposite. A board that can verify does not need to interrogate, which makes meetings shorter and decisions faster. A board that cannot verify compensates by asking more questions, requesting more detail, and adding sections to the pack, which is how packs become sixty pages. Independence is the cheaper equilibrium for everyone.
14. Building the Board Reporting Standard
Step 1, Have the board set the standard
- The reporting standard should be agreed by the board, not proposed by management. A standard management sets will optimize for what management can comfortably produce.
- Write it as a short document naming required blocks, the four oversight signals, and a page budget. Two pages is enough.
- Include an explicit expectation that every pack carries at least one genuinely open item.
Step 2, Fix the traceability layer before the format
- Establish whether any figure in the pack can be traced to an owner, a record, and a date. If not, that is the first project and no formatting work will substitute for it.
- Connect the systems that hold execution data so figures arrive rather than being collected, Profit.co syncs through native integrations with bi-directional updates, which is what makes a board figure defensible under questioning.
- Ensure funded work links to objectives, so portfolio questions have answers. This traceability from business case through benefits realization sits in the strategic portfolio management module.
Step 3, Decide what reaches the board unfiltered
- Name the indicators that will be presented as generated, with distributions intact, alongside rather than replaced by commentary.
- Agree that management commentary sits next to the system view rather than in place of it, so divergence between the two is visible.
- Set the as-of convention: every major figure carries its date on the page, not in an appendix.
Step 4, Freeze the structure and run the loop
- Hold the structure for at least four meetings so the board can read trends across packs. Comparability is worth more than any individual improvement.
- Carry decisions forward with their current state, so each meeting continues the last rather than restarting.
- Review the standard annually against the independence test, and retire sections that have not informed a decision in a year.
Profit.co reports most customers complete setup and run their first cycle within two to four weeks, with enterprise rollouts involving custom integrations typically taking four to eight weeks, which means the traceability layer is realistically a one-quarter project rather than a multi-year one. The delivery-side view of the same governance chain sits on Profit.co’s page for PMO leaders.
Build a board pack your directors can verify rather than accept
Frequently Asked Questions
Reporting designed to let a board exercise oversight of strategy, monitoring direction, questioning the account it is given, and holding management accountable for execution. It differs from executive reporting in purpose rather than depth: executive reporting supports managing the work, board reporting supports assessing whether the work is being managed well.
Four oversight signals beyond the standard content: traceability from any claim back to its source record; leading indicators presented as generated rather than summarized; variance shown across periods rather than within one; and pending decisions, unvalidated assumptions, and material risks surfaced rather than resolved in advance. Plus a stated as-of date and comparison basis on every major figure.
Executive reporting supports action inside the cycle, reallocating, unblocking, adjusting priorities. Board reporting supports oversight of whether the strategy remains right and whether management is executing it competently. Content that supports no board decision should not be in the pack, which is why delivery-level detail belongs in executive reporting and not board reporting.
Short enough to be read in full before the meeting, with a fixed page budget where additions require retirements. One page per strategic priority is a workable ceiling. Length is usually a symptom rather than a problem in itself, packs grow because directors cannot verify claims and compensate by requesting more detail.
Each scheduled meeting, typically quarterly, with content weighted differently by point in the cycle: plan soundness and coverage at cycle open, leading indicators and early variance in early execution, multi-period variance and reallocation at mid-cycle, and full-year variance with benefits realized against promised at close. Traceability is a standing property rather than a meeting-specific item.
The reassurance pack, every priority green, every risk mitigated, no open questions. It reads well and supports no oversight. A useful diagnostic is to count the items in a pack that could lead a director to challenge management; if the answer is zero, the document is a briefing rather than a board report.
Yes, and a pack with none is a warning sign. Bringing a live question to a board can feel like admitting the executive team could not settle it, but the opposite reading is more accurate: a management team confident enough to show an open question is one that is not managing its board. A reasonable standard is at least one genuinely open item per pack.
Apply the independence test: could a director, using only the pack, reach a conclusion that differs from management’s? Passing requires raw distributions rather than only summaries, stated comparison bases, multi-period variance, and open items. A board that can verify asks fewer questions and decides faster, which is why independence is the cheaper equilibrium for management too.


